
Listen to the audio version of this article (generated by AI).
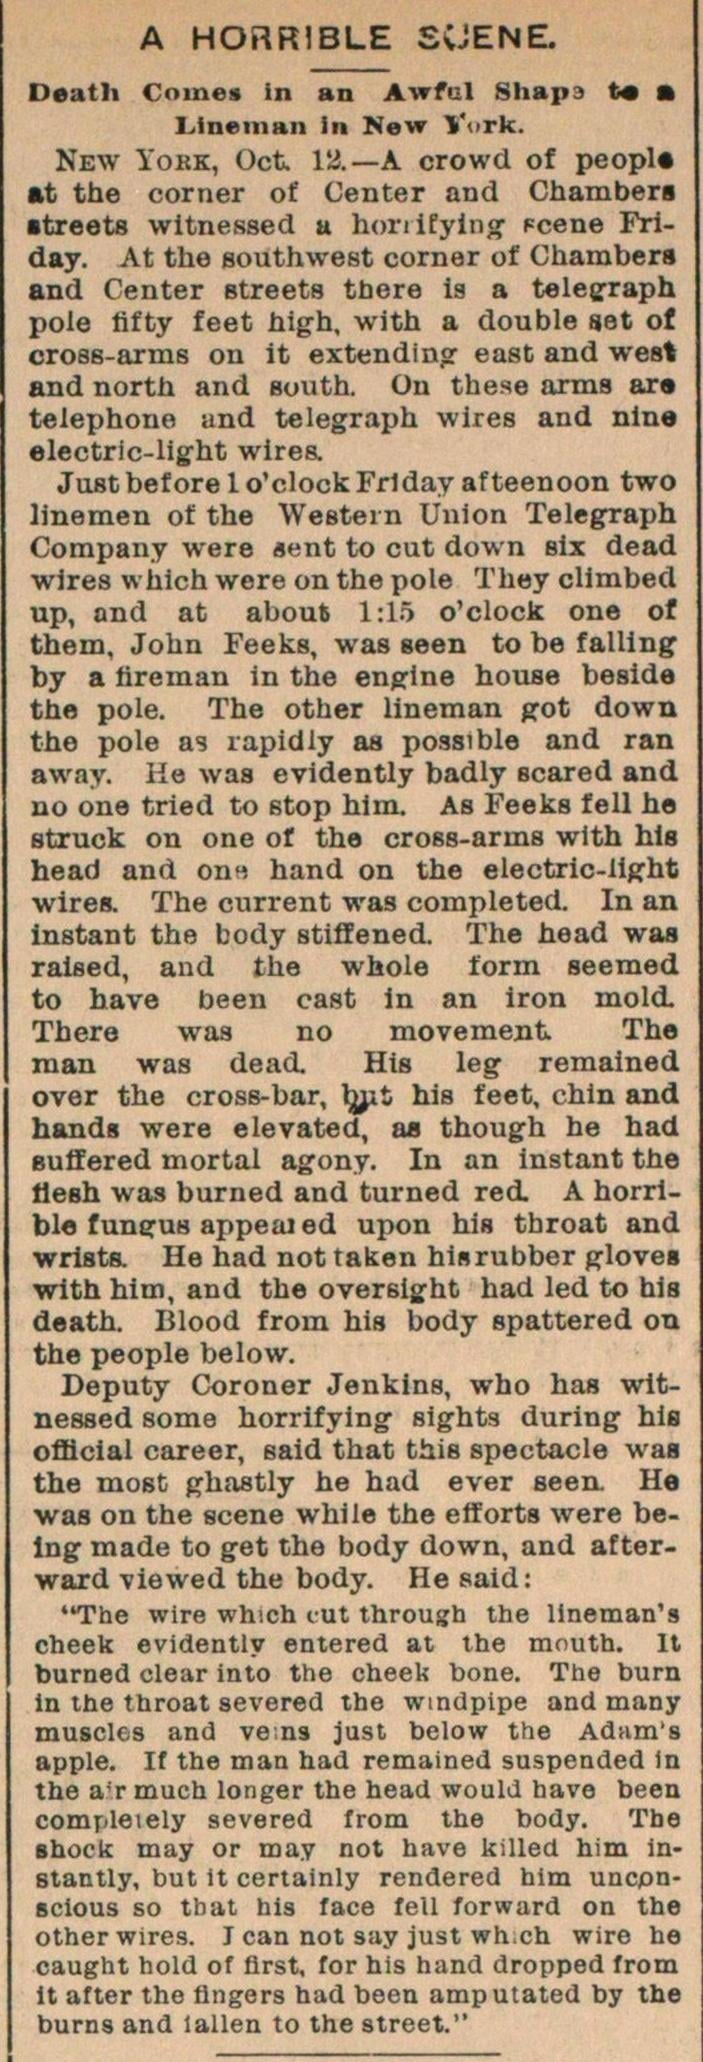
One October, in the late 1880s, just before 1 p.m., two Western Union linemen climbed a pole in lower Manhattan to cut down dead electrical wires. Only one returned alive.
Atop the 50-foot-high pole, crowded with electric wires, a nearby fireman caught a terrifying glimpse of the grisly scene.
One of the men, John Feeks, fell from the pole, struck a crossarm, and came into contact with an electric wire.
At that moment, “The current was completed,” the Ann Arbor Register reported.
Feeks’s body stiffened. His leg remained hooked over the crossbar.
“There was no movement.”
His coworker scrambled down and fled. Below, people witnessed a scene Deputy Coroner Jenkins described as the most ghastly he had ever seen. Even afterward, Jenkins could not say whether the current had killed Feeks immediately: “The shock may or may not have killed him instantly.”
The horror soon became public fury, and a full-blown electric wire panic. Building owners cut wires above their rooftops. Newspapers demanded accountability. The next day, Mayor Hugh Grant ordered unsafe wires removed.
New York had already passed legislation requiring wires to go underground. Feeks’s death gave that longstanding fight a terrible urgency.
Put yourself in an investor’s shoes.
A technology that promised to transform everyday life had become a source of public terror. As a result, authorities ordered its infrastructure torn down.
Would you have bet on the future of electricity?
Two years later, a traveling lineman named Henry Miller organized a convention in St. Louis that founded what became the International Brotherhood of Electrical Workers. Today, electrical power-line installers and repairers earn a median $95,320 a year, or nearly twice the median for all occupations.
The lesson I draw is that a technology’s dangers can make the work of building and maintaining it more valuable.
And that brings me to AI.
When investors see backlash, they tend to ask how much growth it could destroy. I think there’s another question worth asking:
How do we solve the problems standing in our way?
That’s the question I’d bring to the AI debate in 2026. Because investors who see only the panic may be putting fear of the unknown ahead of the opportunity.
The Money Isn’t Going Anywhere
Meanwhile, the demand behind this buildout just got locked in.
Anthropic’s leaked initial public offering (IPO) prospectus reportedly shows roughly $518 billion in compute and infrastructure commitments. About 80% of that is noncancelable or payable regardless of usage, with obligations stretching into the 2030s. And OpenAI’s annualized revenue run rate is approaching $70 billion, up more than 70% since the start of the third quarter.
So, the backlash isn’t stopping AI dollars. Rather, it’s rerouting them toward the companies that build, wire, and power data centers on-site.
Follow the paychecks and you’ll see it. Experienced electricians now command north of $100,000. Postings for welders and pipefitters are up 164% year over year. Welders can graduate high school and earn $65,000 to $75,000 in short order, with almost unlimited overtime.
Unlike the internet boom, which mostly rewarded advanced degrees, this is a blue-collar resurgence. And it shows up in the order books.
EMCOR Group Inc. (EME) ended June with a record $17.1 billion in remaining performance obligations, up 44% year over year. Comfort Systems USA Inc. (FIX) posted a record $14.1 billion backlog, up 73%. Quanta Services Inc. (PWR) is sitting on $53.4 billion.
On the power side, Bloom Energy Corp. (BE) topped $1 billion in quarterly revenue for the first time, up 166%. Caterpillar Inc. (CAT), whose generators are a go-to for on-site power, is one of our favorite ways to play this. And Anthropic just signed an $11.6 billion, seven-year compute deal with Akamai Technologies Inc. (AKAM) to tap its distributed cloud network.
Follow the Builders
Now take that logic all the way.
If land, water, and angry neighbors are the constraint, what happens when you build somewhere with no neighbors at all?
This week, SpaceX (SPCX) sent Starship into orbit for the first time. Elon Musk says the company’s first AI compute satellites, powered by Nvidia Corp. (NVDA) chips, will launch in late 2027 and hit “significant scale” in 2028. Alphabet Inc.’s (GOOGL) Google is sending its own AI chips into orbit this week.
It’s early, and it’s expensive. Barclays estimates orbital compute costs roughly three times as much as building on the ground. For the next few years, the boom here on Earth keeps rolling.
But I keep coming back to one thing in particular…
In 1889, Thomas Edison and George Westinghouse dominated the headline, which locked in their war of the currents. The steadier fortunes went to the builders who strung the wire, dug the conduits, and supplied the equipment that electrified the country.
The same thing is happening today. Only the headlines are about moratoriums and chatbots. Wherever new infrastructure goes, a class of builders and suppliers follows. They rarely get the magazine covers, but they’re usually where the money is made.
Orbital data centers won’t be any different. Everyone is watching SpaceX. Yet, far fewer are watching the companies that will build, launch, power, and connect the compute Musk wants to put in space.
That supply chain is what I call “XPANSE.” And I think it could be one of the most asymmetric setups in the entire AI trade.
I’ve put together a full briefing on it, including the companies I believe are best positioned to profit as this buildout leaves the ground.